All Categories
Featured


Choosing the Best Annuity for Retirement
Table of Contents
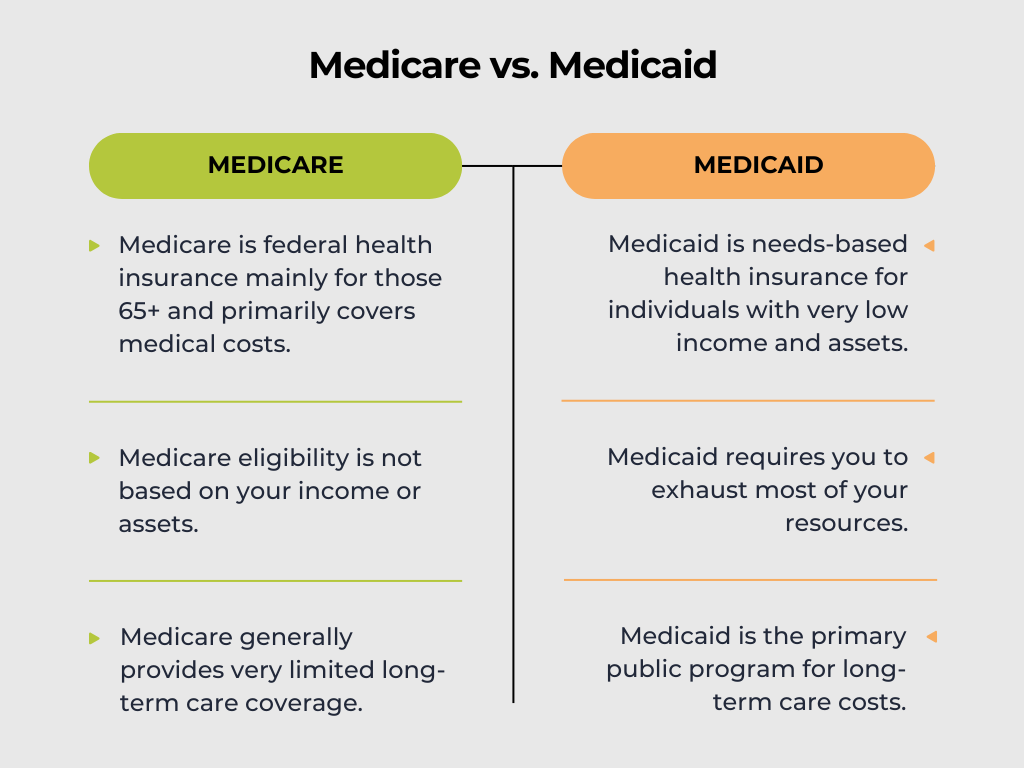
Does Medicare cover long-term care? Normally, the answer is no. Initial Medicare does not pay for custodial care, which is assist with daily activities like bathing, dressing, or utilizing the bathroom. Most individuals who need long-lasting care require non-medical help. While Medicare Part A and Medicare Part B are vital for health center stays and physician sees, they are not developed for long-term stays in a nursing home or helped living facility.
In spite of our efforts to make this website accessible for everybody, there might still be some pages or sections that are not entirely available, are in the process of ending up being accessible, or do not have a suitable technological option to make them accessible. Nonetheless, we are always making every effort to enhance our accessibility by adding, upgrading, enhancing its options and features, and including new innovations.
If you wish to call this website's owner, please utilize the contact form on the website. - With this tool, users can customize font size, style, letter spacing, and line height for improved positioning and readability. - Users can customize their color contrast profiles to light, dark, desaturated, and monochrome.
- Users can allow focus mode to highlight the current page information based on their mouse movement.
One of the most typical and expensive misconceptions in retirement planning is the presumption that Medicare will pay for long-term care. Medicare is a federal health insurance coverage program for people age 65 and older, and for particular more youthful people with impairments.
Long-Term Care Alternatives Beyond Medicare
Short-term skilled care after a qualifying medical facility stay of at least 3 days. Protection adds to 100 days per advantage period, with days 120 completely paid and days 21100 based on a significant everyday copay. Limited home health for clinically required proficient care. Hospice care. Medicare was not developed to spend for the ongoing custodial care that a lot of long-term care claims include.
Whether the care is delivered in the house, in an assisted living community, in memory care, or in an experienced nursing center, Medicare will not fund it once the short-term skilled window closes. 2 words bring a lot of weight in this area: and. care is what a licensed clinician provides: injury care, IV treatment, physical rehabilitation.

When the short-term skilled window closes and care continues, the costs moves totally to the family (or, in some cases, Medicaid after assets have actually been spent down). Long-Term Care Insurance was created specifically for this custodial care.
Lots of agreements also include care coordination services that help a family browse providers and documents. Think of it in this manner: Medicare covers the medical side (healthcare facility, physician, short-term rehabilitation). Long-Term Care Insurance coverage covers the daily-living side once the medical piece is done. Both belong in a real retirement plan; they do various jobs.
Protecting Your Savings With Accident Coverage
Partnership-qualified Long-Term Care policies, available in the majority of states, supply extra Medicaid possession security if benefits are ever exhausted. If your retirement strategy assumes Medicare will handle a long-lasting care occasion, it does not.
Presuming Medicare will do the task is the strategy that fails. Ready to talk it through? A short discussion is the fastest way to see whether the concepts here fit your scenario. Keep reading U.S. Department of Health and Person Services, (care statistics and meanings). Genworth Expense of Care Survey (yearly industry expense standard).
National Association of Insurance Commissioners, A Buyer's Guide to Long-Term Care Insurance. Illustrative rates in this article is for education only and does not represent a quote for any particular individual or policy.
Retirement Planning Fontana CAHave you thought about how you would desire to receive care if you can't look after yourself in the future? Have you prepared to pay for it? Someone turning age 65 today has nearly a 70% chance of needing some type of prolonged care services and support in their remaining years, according to the Administration for Community Living.
Managing Future Medical Costs in 2026
Comprehending the difference between Short-term Care insurance vs. Long-term Care insurance can help you produce a care strategy that ensures your finances are well secured. Long-lasting Care insurance assists cover the assistance that you'll require when you can no longer perform tasks by yourself from chronic illness, special needs, and/or disability.

Latest Posts

Why Seniors Need Critical Illness Policies

Variable and Fixed Annuities Explained
The Advantage of Using Long Financial Tools