All Categories
Featured


Variable and Fixed Annuities Explained
Table of Contents
Hybrid policies can protect both earnings and estate. Consist of real-life care scenarios: dementia, movement loss, single-spouse requirement. At home vs. facility, family participation, care quality. Medicare is essentialbut it's not enough on its own. The finest time to plan for long-term care is when you don't need it. Due to the fact that the comfort you'll have later on begins with the choices you make today.
works as the Chief Financial Investment Officer at Langan Financial Group. In this function, he handles financial investment portfolios, acts as a fiduciary for group retirement plans, and talks to customers concerning their monetary goals, threat tolerance, and property allotment. With a focus on ERISA Law, Alex finished orgasm laude from Widener Commonwealth Law School.
Alex is also enthusiastic about providing back to the community, and has gotten involved in The Structure of Enhancing Neighborhoods' Emerging Philanthropist Program, volunteers at his church, and acts as a board member of Samara: The Center of Individual & Household Growth. Beyond work and offering, Alex enjoys his time with his partner Sarah, and their 3 kids, Rory, Patrick, and Ava.
Comparing Long-Term Care Coverage Versus Medicare
Your business. Your family's future. Each is worthy of thoughtful planning that begins with what matters to you. Langan Financial Group provides monetary preparation and investment management for people, families, and organization owners. With workplaces in Camp Hill and York, Pennsylvania, we serve clients throughout Central Pennsylvania. We help you resolve concerns about retirement income, financial investment choices, Social Security, and how taxes may impact your financial strategy.
From there, we help you examine your alternatives and develop a plan that can progress as your life modifications. We likewise assist companies and organizations evaluate workplace retirement strategies and comprehend their responsibilities as strategy sponsors. The content is established from sources believed to be offering precise details. The details in this material is not meant as tax or legal advice.
The opinions expressed and material supplied are for general info, and need to not be considered a solicitation for the purchase or sale of any security.
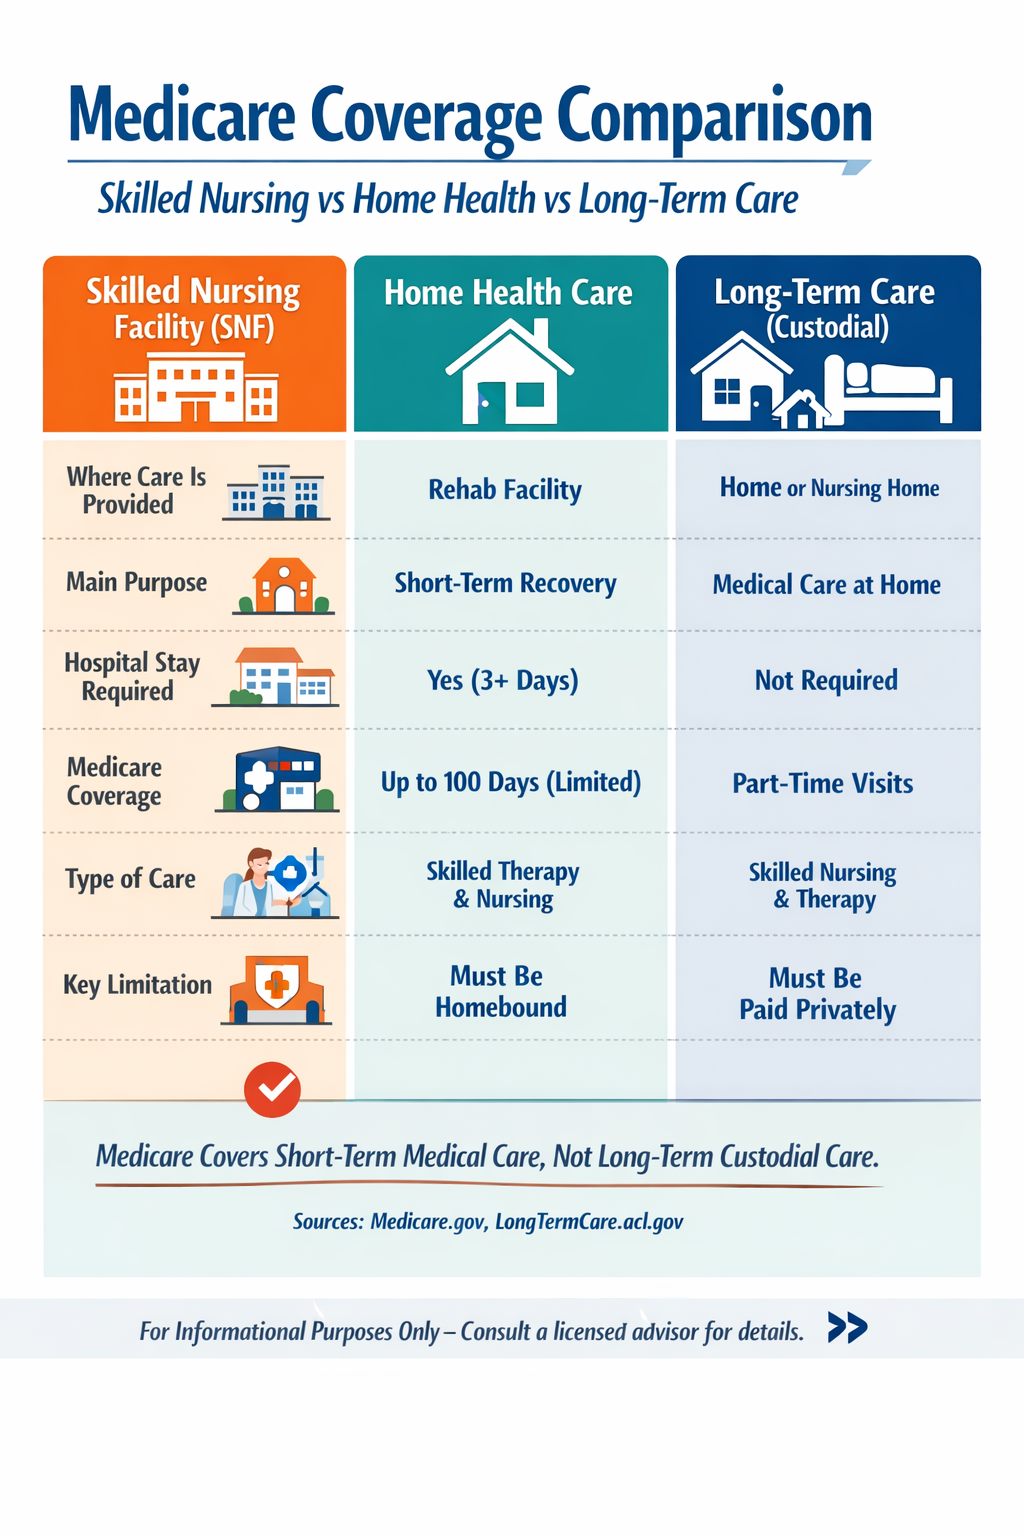
Most Americans erroneously believe Medicare will cover their long-lasting care requirements in retirement. This vital misunderstanding can lead to devastating monetary repercussions when care is eventually required. Medicare offers limited protection for long-lasting care services: As much as 100 days maximum Requires a certifying 3-day hospital stay first Days 21-100 require an everyday copayment ($200+ daily in 2025) Must reveal constant enhancement to preserve coverage Limited protection Needs medical professional certification of medical requirement Need to be skilled nursing care (not custodial) Care need to be part-time or intermittent just the assistance with activities of daily living that Medicare does not cover:.
Critical Illness Coverage for Senior Adults
The relationship in between long-lasting care (LTC) and medical care covered by TRICARE, Medicare, or company health care can be complicated. Examples of medical insurance include your health strategy at work, TRICARE or TRICARE for Life, and Medicare. These cover medical costs connected to the treatment of an illness or injury.
After treatment, recuperation or recovery is not covered. It's about the requirement for support when you can't perform regular activities of life and you need assist to operate.
Many individuals believe of LTC as nursing home care. A better description would be stay-at-home care.
Serious Illness Coverage for Older Adults
A lot of Americans mistakenly believe Medicare will cover their long-term care requirements in retirement. This important misunderstanding can result in devastating financial effects when care is ultimately required. Medicare offers limited coverage for long-lasting care services: Up to 100 days optimal Needs a certifying 3-day medical facility stay first Days 21-100 need a day-to-day copayment ($200+ daily in 2025) Must reveal continuous enhancement to preserve coverage Limited protection Needs medical professional certification of medical requirement Should be knowledgeable nursing care (not custodial) Care need to be part-time or periodic just the assistance with activities of daily living that Medicare doesn't cover:.
While it may be difficult to think of now, it's likely that you'll need some kind of health care or daily living help as you age. Individuals frequently think that Medicare covers long-term care, either in your home or in a nursing center, however sadly, that's not the case. Medicare doesn't cover assisted living, proficient nursing, or long-term care.
If you're unable to leave your house for medical or restorative care, Medicare will spend for home healthcare services. Notably, Medicare will not cover 24-hour care. Long-lasting Care (LTC) Insurance is developed to cover long-lasting services and support not covered by standard medical insurance or Medicare. It can consist of a variety of advantages for individuals who need continuous medical attention and/or custodial care with daily activities like eating, bathing, or movement in facilities from helped living to full-time, in- home custodial care to a personal space in a nursing facility.
The cost of a long-term care policy is based on age, preferred advantage quantity and any fringe benefits you choose to consist of. That's why it is necessary to identify your long-term care requirements and level of security before it becomes an emergency situation. Considering long-term care is a foundation in any monetary plan, and there are many choices to pick from based upon your monetary circumstance and requirements.
Retirement Planning Santa Ana CACritical Illness Protection for Senior Adults
It's much better to be overprepared and covered, than underprepared and economically devastated.
Medicare does not cover your long-lasting nursing care or 24/7 in-home services, nor does it spend for your custodial care which includes your daily activities such as consuming, bathing, and dressing.
Why do lots of monetary advisors inform customers they can self-insure for long-lasting care however advise them to purchase extra protection to Medicare? This concern has actually afflicted me for thirty years. The main factor this subject is so crucial is that the most typical objection my group and I encounter relating to long-term care insurance is, "I'm going to self-insure." Lots of people truly desire the protection of insurance coverage, yet their financial consultant frequently recommends that self-insurance is preferable.
They regularly buy Part D drug coverage, either matched with Medicare Benefit or a conventional Medicare supplement. Financial consultants hardly ever advise versus buying supplemental Medicare coverage. Only 6% of Medicare beneficiaries do not have any supplemental coverage. 1 Current research indicates that the average Medicare Supplement premium is approximately $2,600 yearly.
LTC Alternatives Beyond Medicare
The typical claim payment is considerably less than $4,000 per year, according to Telos Actuarial. For 2026, there is a $2,100 cap on drug coverage under Part D. If you don't believe me that the claim payments are little, look at the Description of Benefits that shows the claim payments from your Medicare Supplement or Part D drug plan.

Latest Posts

Why Seniors Need Critical Illness Policies
Variable and Fixed Annuities Explained
The Advantage of Using Long Financial Tools